
Post-FOMC value migrated lower after ESZ6 covered the 7693.25 and 7585.00 nVPOCs, establishing 7622.50 as the session’s new center of trade.
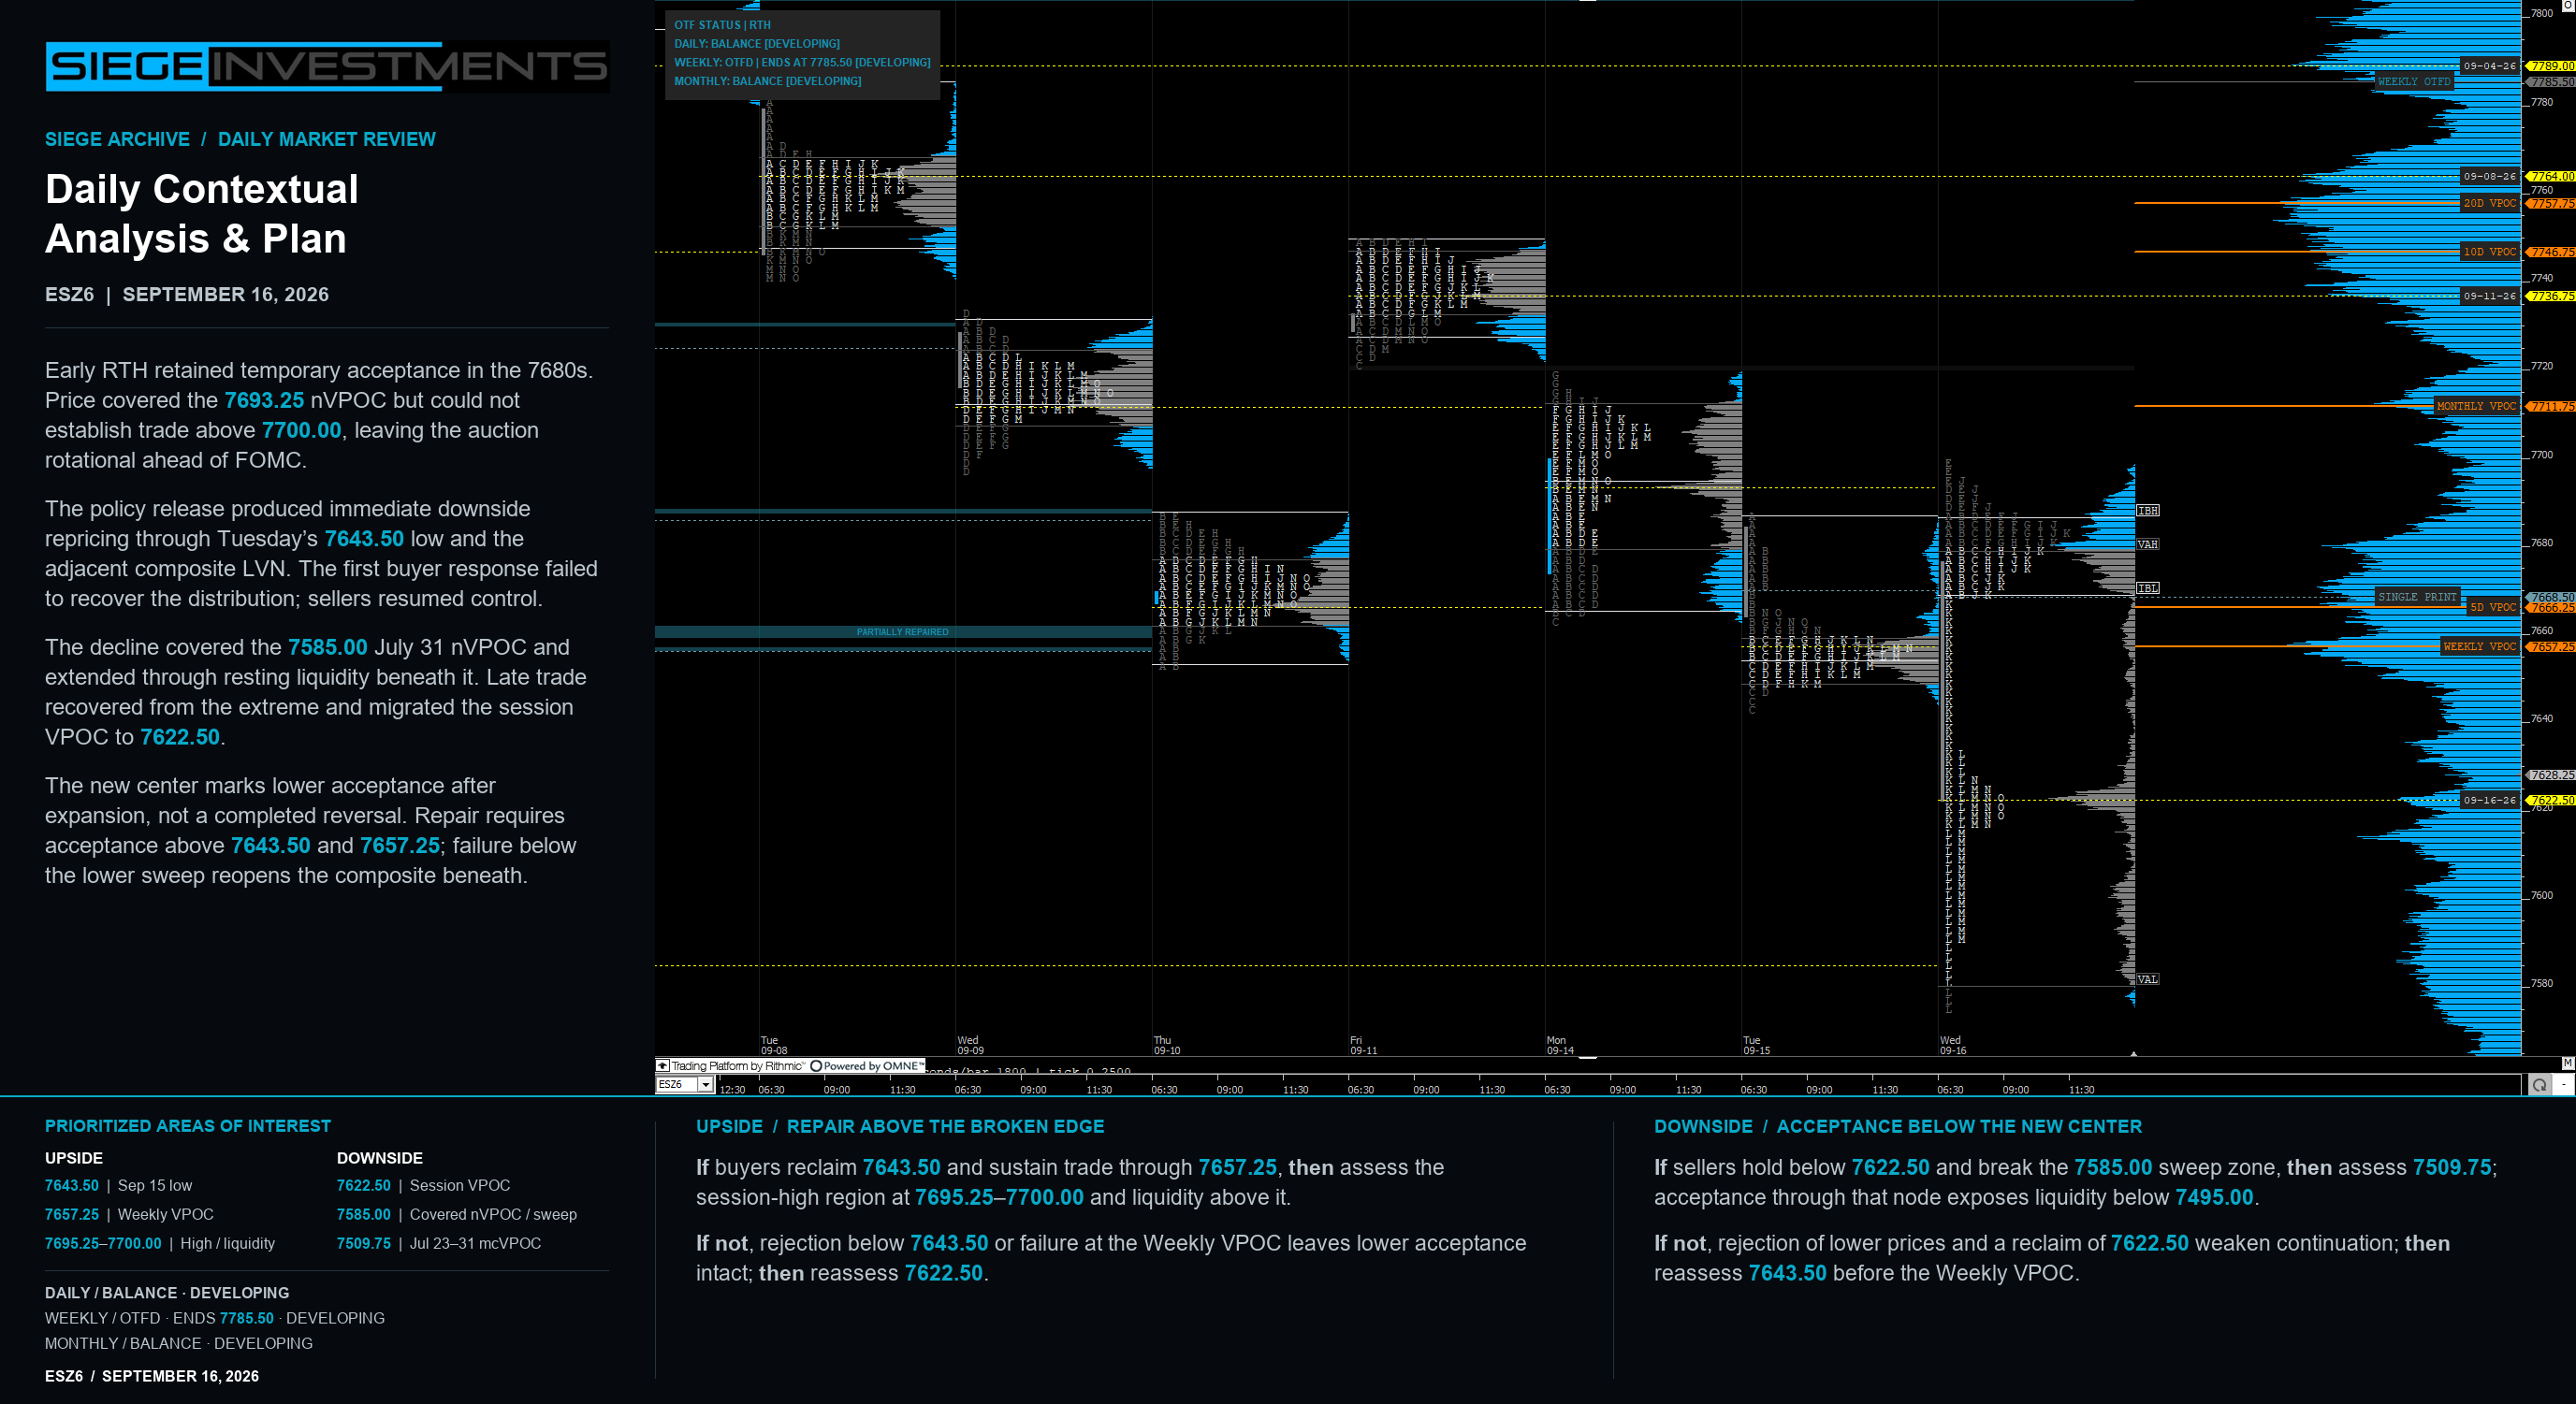
ESZ6 entered Wednesday with little directional progress during the overnight session. Early RTH continued that condition as trade found temporary acceptance in the 7680s, rotating through the nearby distribution rather than sustaining an auction beyond either edge. Price covered Tuesday’s 7693.25 nVPOC, but repeated trade near the upper boundary failed to establish acceptance above 7700.00.
That distinction matters. Covering a naked VPOC resolved unfinished business from the prior session; it did not, by itself, create upside continuation. The market had reached a known price check and continued to conduct two-sided business around established volume while awaiting the scheduled policy catalyst.
The Federal Open Market Committee raised its target range by 25 basis points to 3.75%–4.00%. The release coincided with an immediate downside repricing. Sellers carried the auction out of the morning distribution and into Tuesday’s low near 7643.50, where the composite low-volume transition produced an initial responsive bid.
That response was meaningful but incomplete. Buyers generated a reaction from the prior-session boundary, yet they could not recover the distribution that had just been vacated. Once the rebound failed to restore acceptance above the broken structure, selling resumed and the market continued to explore lower prices through the thinner portion of the composite.
The distinction between reaction and reversal is central here. A response at a known low-volume boundary shows that the location mattered. It becomes a reversal only if the ensuing auction can reclaim and hold the structure above. Wednesday’s auction did not meet that test.
The second leg lower traversed the irregular, lower-volume portion between the two larger composite distributions. In doing so, the session filled in portions of the previously toothy profile and covered the 7585.00 naked VPOC from July 31. Price then extended below that reference, triggering the resting liquidity beneath it before establishing the session low.
Once covered, the 7585.00 nVPOC was removed from the list of untouched references. It remains a useful location for evaluating future acceptance or rejection, but its role has changed: it is now a tested structural boundary rather than unresolved unfinished business.
Late trade recovered from the extreme and developed a session VPOC at 7622.50. That migration shows where the market ultimately conducted the greatest concentration of business after the policy-driven expansion. It does not erase the earlier selling initiative. It identifies the new short-term center of trade from which the next auction can either repair upward or resume exploration lower.
The first meaningful upside check is Tuesday’s low at 7643.50. A recovery to that level would revisit the boundary that initially produced responsive buying after the announcement. Buyers must do more than touch it; they need to regain acceptance above it before the 7657.25 Weekly VPOC becomes the next structural test.
If buyers reclaim 7643.50 and sustain trade through 7657.25, then the auction can begin repairing the post-FOMC breakdown toward the upper portion of Wednesday’s range. The next major test is the session-high region near 7695.25–7700.00, where the morning auction failed and resting liquidity remains above the high.
If not, rejection beneath 7643.50 or a failed attempt to hold the Weekly VPOC would leave the lower distribution in control; then rotation back toward 7622.50 remains the nearer alternative. Repeated trade around the migrated VPOC without recovery of the broken upper structure would indicate continued acceptance at the lower price area.
The immediate downside question is whether the market can hold the newly developed center at 7622.50 and remain above the 7585.00 sweep zone. The composite profile below is comparatively broad and high volume, so continuation may develop as rotational trade rather than a clean vertical traverse.
If sellers maintain acceptance below 7622.50 and subsequently break the lower edge established around the 7585.00 sweep, then the next major higher-timeframe price check is the July 23–31 composite VPOC at 7509.75. Continued acceptance through that node would bring the resting liquidity below 7495.00 into focus.
If not, rejection of lower prices followed by a reclaim of 7622.50 would weaken immediate downside continuation; then assess whether price can rotate back to 7643.50 and begin repairing the separation left by the announcement. A failed lower probe is evidence only after the market recovers the references it previously lost.
Wednesday began in temporary balance and ended with a decisive relocation of value. The auction covered the 7693.25 and 7585.00 naked VPOCs in the same session, rejected the upper distribution, and established a lower center of business at 7622.50. Daily balance remains developing on the supplied TPO, while weekly OTFD remains developing and ends at 7785.50; monthly balance is also developing.
The next session opens with clear conditional work. Above 7643.50, buyers can begin testing whether the post-announcement decline is being repaired. Below the 7622.50 center and the 7585.00 lower boundary, sellers can begin testing whether the broader lower composite will be re-auctioned toward 7509.75. Between those locations, the market remains engaged in two-sided trade within the newly accepted lower distribution.
Source for the policy decision: Federal Reserve, September 16, 2026 FOMC statement.