
An overnight-low sweep rejected lower prices, but the recovery stalled at the 7687.00–7688.00 upper boundary. RTH later accepted trade around the 7657.25 Weekly VPOC.
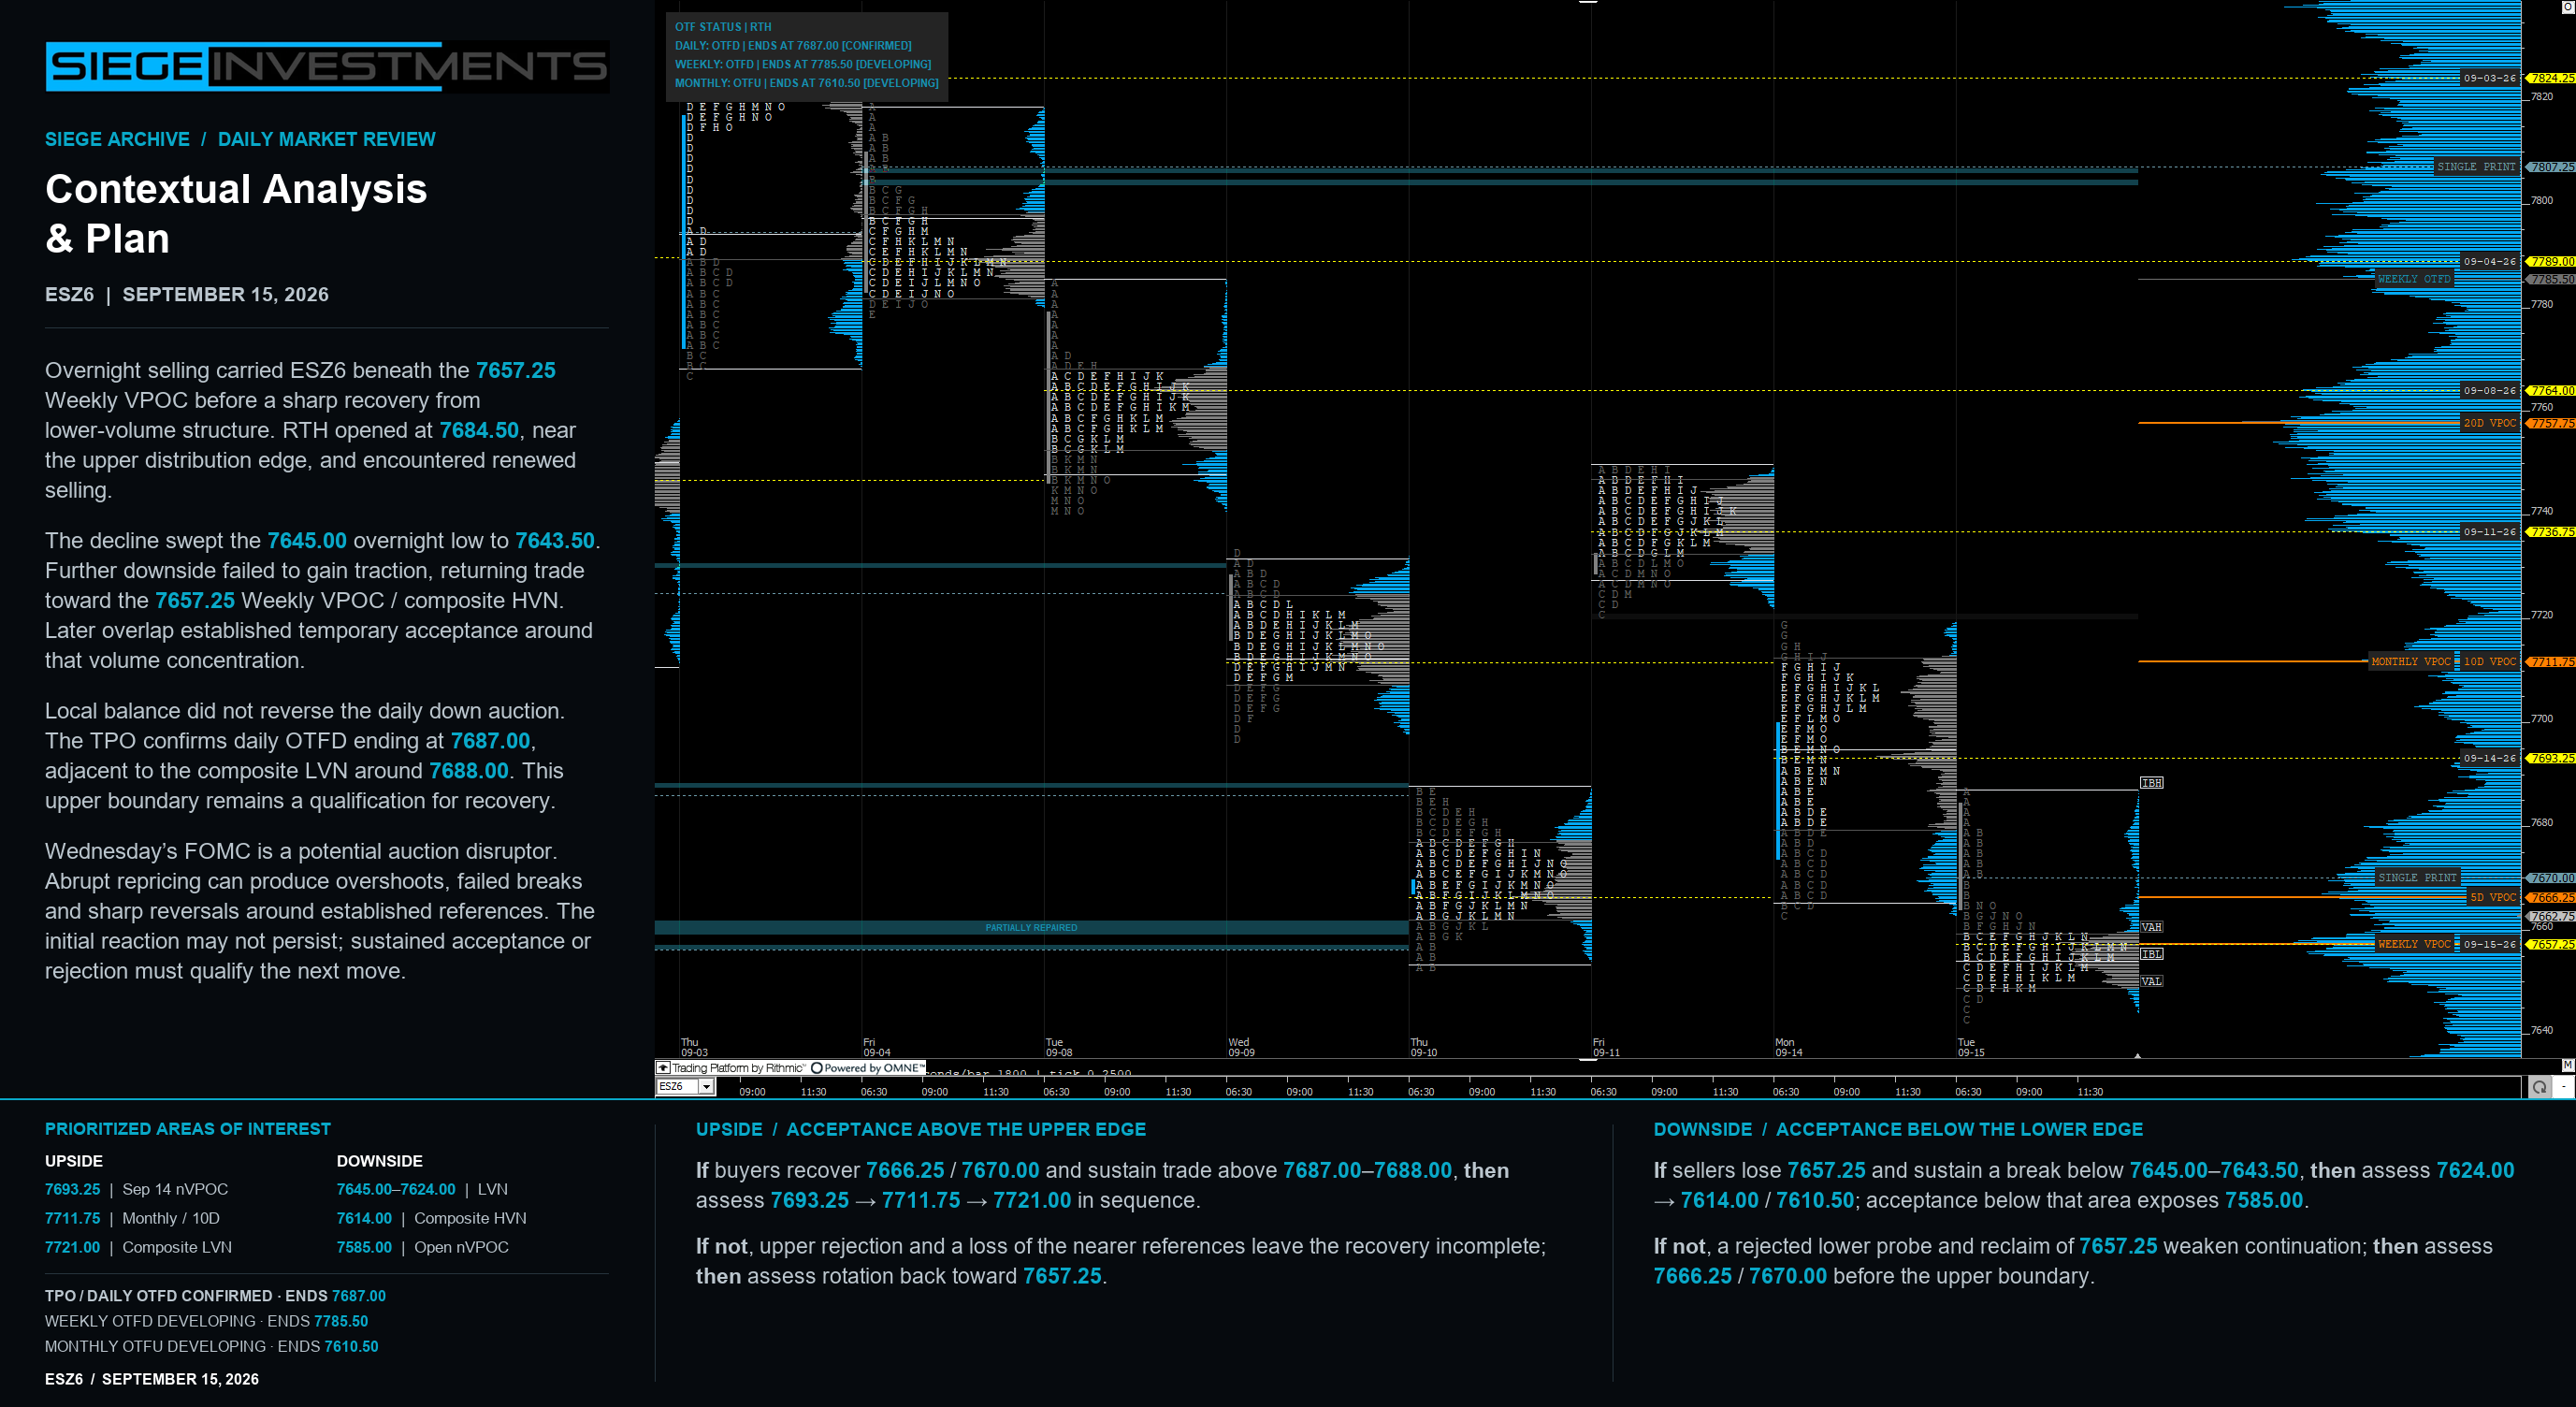
Tuesday’s ESZ6 auction moved from overnight selling to a lower regular-session balance. Sellers carried the extended-hours auction beneath the 7657.25 Weekly VPOC into the thinner structure below, where the decline reversed sharply. That V-shaped recovery demonstrated a response to lower prices, but the regular session still had to establish whether buyers could sustain the recovery beyond the surrounding distribution.
They could not do so at the open. RTH began at 7684.50, near the upper side of the distribution, and encountered renewed selling. The TPO identifies 7687.00 as the daily OTFD termination reference, adjacent to the composite LVN around 7688.00 identified on the higher-timeframe chart. These are neighboring references with different functions: one defines the daily sequence; the other marks a thinner boundary in the composite. Together, they frame the upper test that buyers were unable to sustain.
The ensuing decline returned price to the overnight low at 7645.00 and extended modestly beneath it to the session low at 7643.50. Describing this as a sweep is more precise than calling it an untouched retest. The extension failed to produce sustained trade lower; the subsequent recovery returned the auction toward 7657.25, where the Weekly VPOC aligned with the composite volume concentration highlighted in the session notes.
Later RTH trade overlapped around that reference, developing a concentration of time and volume after the morning decline. This was evidence of temporary acceptance at lower prices. It was not evidence that buyers had recovered the full morning range or resolved the broader down auction. The market had stopped extending lower and begun conducting two-sided business within a narrower portion of the distribution.
The distinction between local balance and timeframe direction matters here. The supplied TPO reports Daily OTFD confirmed, ending at 7687.00; Weekly OTFD developing, ending at 7785.50; and Monthly OTFU developing, ending at 7610.50. The later intraday balance describes how trade developed after the decline; daily OTFD describes the directional sequence across sessions. A pause around the Weekly VPOC can coexist with that sequence until its termination reference is breached.
The first question is whether buyers can retain 7657.25 and carry the recovery through 7666.25, the 5D VPOC, and the TPO’s 7670.00 single-print reference. Those nearer structures precede the 7687.00–7688.00 upper boundary. A rotation to that boundary would test the morning rejection; it would not, by itself, establish acceptance in the distribution above.
If buyers sustain trade above that boundary, then the September 14 nVPOC at 7693.25 becomes the next overhead price check. Continued acceptance would bring 7711.75, where the Monthly and 10D VPOCs coincide, into focus. The subsequent structural pivot is the composite LVN around 7721.00, the transition toward the larger distribution overhead. These are the three prioritized upside areas; each remains conditional on clearing the intervening auction.
If not, rejection at the upper boundary followed by a loss of 7670.00 and 7666.25 would leave the recovery incomplete; then rotation back toward 7657.25 remains the nearer alternative. Repeated crossings of the Weekly VPOC without sustained expansion beyond the surrounding structure would support continued two-sided trade.
Beyond 7721.00, the higher distribution contains additional checks at 7736.75 and the HTF chart’s 7746.75 reference before the broader 7754.00–7758.00 high-volume area identified in the review notes. The 7757.75 20D VPOC sits within that upper area. Historical volume makes it a relevant destination if the higher distribution is accepted; it does not make it an inevitable magnet from the current auction.
If sellers establish acceptance beneath 7657.25 and sustain a break below 7645.00–7643.50, then deeper exploration of the identified 7645.00–7624.00 low-volume region becomes relevant. That broad region is a transition to assess, not a single support price. Tuesday’s low tested its upper portion; it did not test the entire zone.
Continued selling through 7624.00 would bring the next composite HVN around 7614.00 into focus. The nearby 7610.50 Monthly OTFU termination reference adds structural significance to the broader area, but it is distinct from the HVN and should retain its own identity. Acceptance beneath the broader 7614.00–7610.50 area would bring the open nVPOC at 7585.00 into focus as the next identified lower reference. That extension requires the intervening structure to give way; the untouched VPOC is an area of interest, not an automatic destination.
If not, a lower probe that fails to gain acceptance, followed by a reclaim of 7657.25, would weaken immediate downside continuation; then assess another rotation toward 7666.25, 7670.00, and eventually the upper boundary if buying persists. A response at the lower edge is useful evidence only when the ensuing auction can hold its recovery.
Wednesday, September 16 brings the FOMC policy announcement at 2:00 p.m. ET / 11:00 a.m. PT, followed by the press conference at 2:30 p.m. ET / 11:30 a.m. PT, according to the Federal Reserve calendar.
This is a potential auction disruptor. Abrupt repricing can produce overshoots, failed breaks and sharp reversals that appear inconsistent with the preceding auction. Established references remain useful locations to assess the response, but the first move through them may not represent durable acceptance. A subsequent reversal can invalidate the initial interpretation just as quickly.
If the post-announcement auction sustains trade beyond a boundary, then reassess the next area of interest using that new evidence. If not, a return inside the prior structure weakens the breakout case; then assess whether rotation toward established volume resumes. The announcement and press conference are separate opportunities for repricing, so a move after the first event should not be assumed to survive the second.
Tuesday left an identifiable center of business around the Weekly VPOC and unresolved boundaries on either side. The next session’s task is to distinguish another rotation within that structure from sustained trade beyond it. The volume concentrations provide the price checks; the lower-volume transitions help define where continuation or rejection must be demonstrated.