
ESZ6 recovered through 7711.75 and retraced most of the weekend gap, but buyers could not reclaim Friday’s range. The auction later balanced around 7693.25.
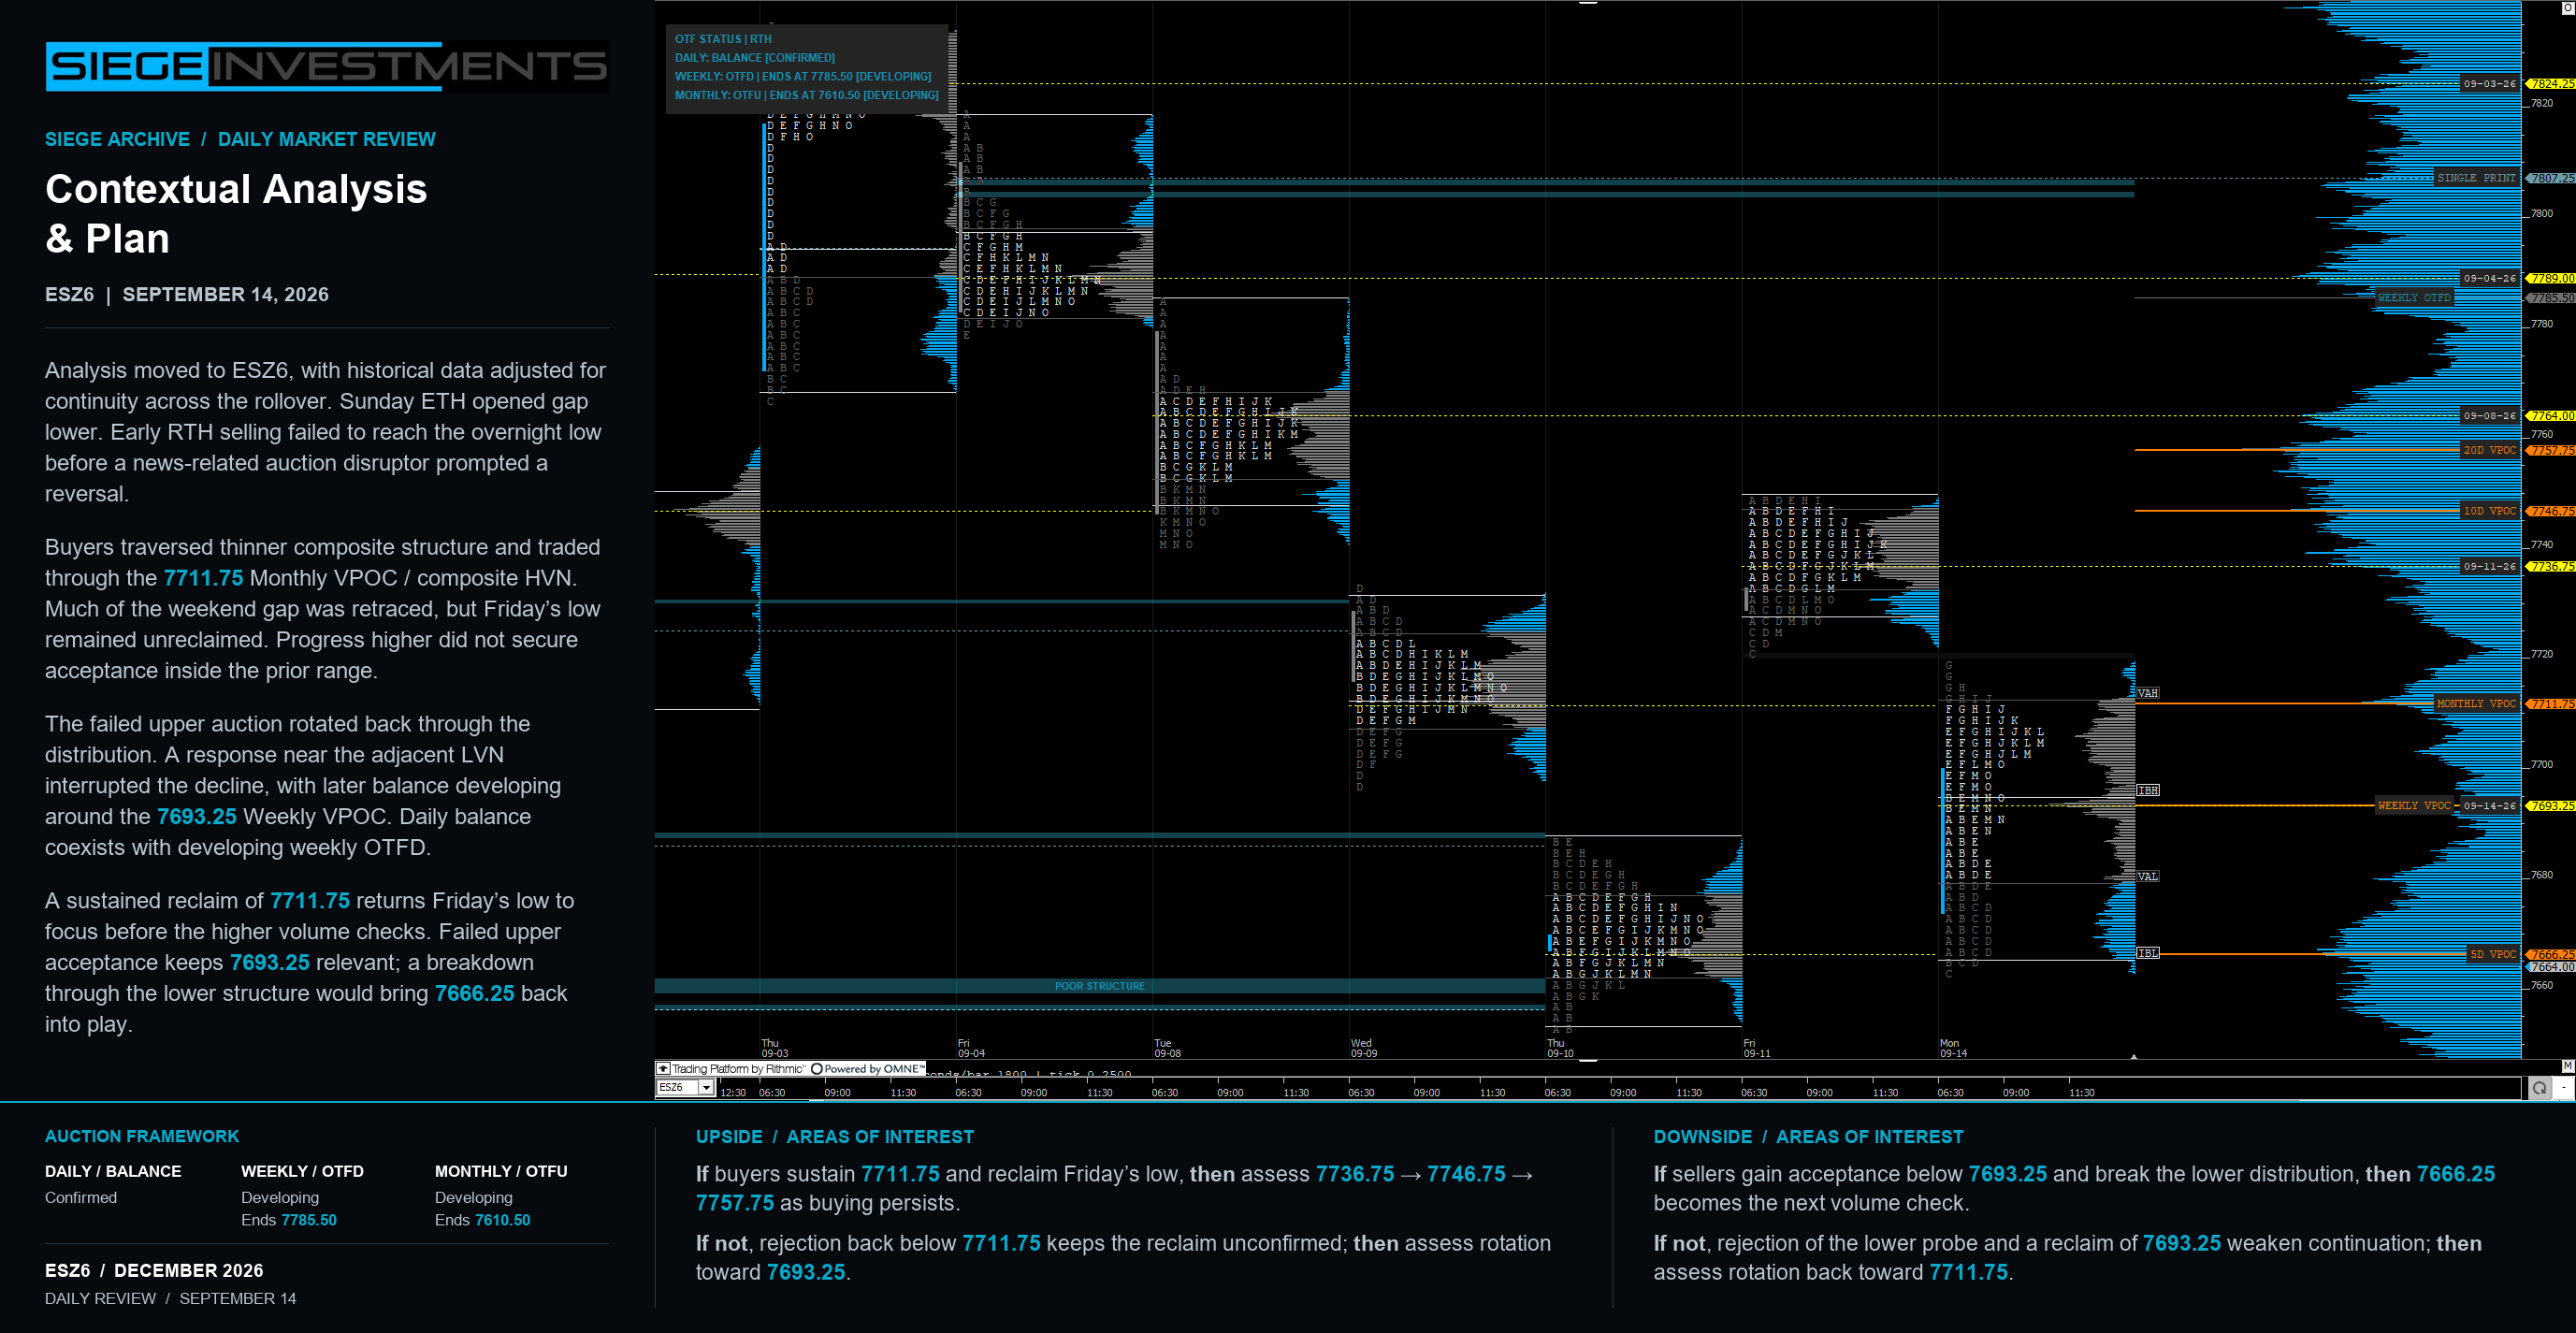
Monday’s analysis transitioned to the December ES contract, ESZ6, with historical data adjusted to maintain continuity across the rollover. All references in this review belong to the updated chart series; prices from the previous contract should not be carried forward without reconciliation.
The week began with a gap lower in Sunday’s extended-hours session. Sellers also held the early initiative at the regular-session open, but the initial downside attempt did not reach the overnight low. A news-related auction disruptor then interrupted that pressure. The early low held through the reversal, and buyers carried trade higher through the lower-volume portions of the composite toward the distributions tested over recent sessions.
The structural significance was the change in the auction’s immediate destination. Selling had failed to extend the early move; the subsequent recovery returned established overhead volume to relevance. Price moved through thinner transitions toward an area where the market had previously conducted more business. That rotation was meaningful, but it still needed acceptance at higher prices to develop beyond a return to prior value.
The 7711.75 Monthly VPOC, aligned with the composite HVN identified on the higher-timeframe chart, became the central price check. Buyers traded through that concentration of historical volume and retraced much of the weekend gap. They were unable, however, to reclaim Friday’s regular-session low and establish trade back inside Friday’s range.
Those are two separate observations. Trading through a VPOC demonstrates that price reached and crossed a reference; it does not establish that the surrounding distribution has been accepted. Likewise, retracing most of a gap is not the same as completing it. Monday’s recovery made substantial progress, but the failure at Friday’s range boundary left the upper auction unresolved.
The subsequent rotation back through the 7711.75 area supplied the more consequential evidence. Buyers had reached the higher-timeframe volume concentration, yet could not sustain the extension beyond it. The auction returned through the distribution toward the adjacent lower-volume transition, where a response interrupted the decline. Later two-sided trade developed around 7693.25, the Weekly VPOC and the session VPOC shown on the supplied charts.
That return to local balance tempered the immediate directional move. It did not establish a broader reversal of the weekly structure. The TPO panel remains Daily BALANCE confirmed, Weekly OTFD developing, and Monthly OTFU developing. The respective weekly and monthly termination references are 7785.50 and 7610.50; they describe timeframe structure, rather than automatic objectives for the next session.
If buyers recover 7711.75 and sustain trade through the upper portion of the distribution, then Friday’s low remains the next qualification for a return to the prior range. A durable reclaim of that boundary would bring the 7736.75 prior-session VPOC into focus, followed by 7746.75 at the 10D VPOC and 7757.75 at the 20D VPOC if buying persists. These are sequential areas of interest. The nearer obstacle must give way before the farther reference becomes relevant.
If not, a failed upper reclaim followed by renewed selling would keep 7693.25 in play as the nearer volume check. Acceptance beneath that reference would shift attention toward the lower side of Monday’s distribution. A sustained failure of that lower structure would bring 7666.25, the 5D VPOC, back into consideration. Losing the Weekly VPOC alone does not establish that the entire lower distribution has failed.
The alternative must remain explicit. If a lower probe is rejected and buyers regain 7693.25, then rotation back toward 7711.75 remains viable. Continued overlap around the Weekly VPOC, without sustained trade beyond the surrounding structure, would favor further two-sided auction rather than a confirmed directional extension.
Monday demonstrated the difference between reaching historical value and securing acceptance beyond it. The coming session’s task is to determine whether buyers can convert another upper test into sustained trade, or whether rejection returns the auction to the lower distribution. Each reference is a price check; the response determines what comes next.