
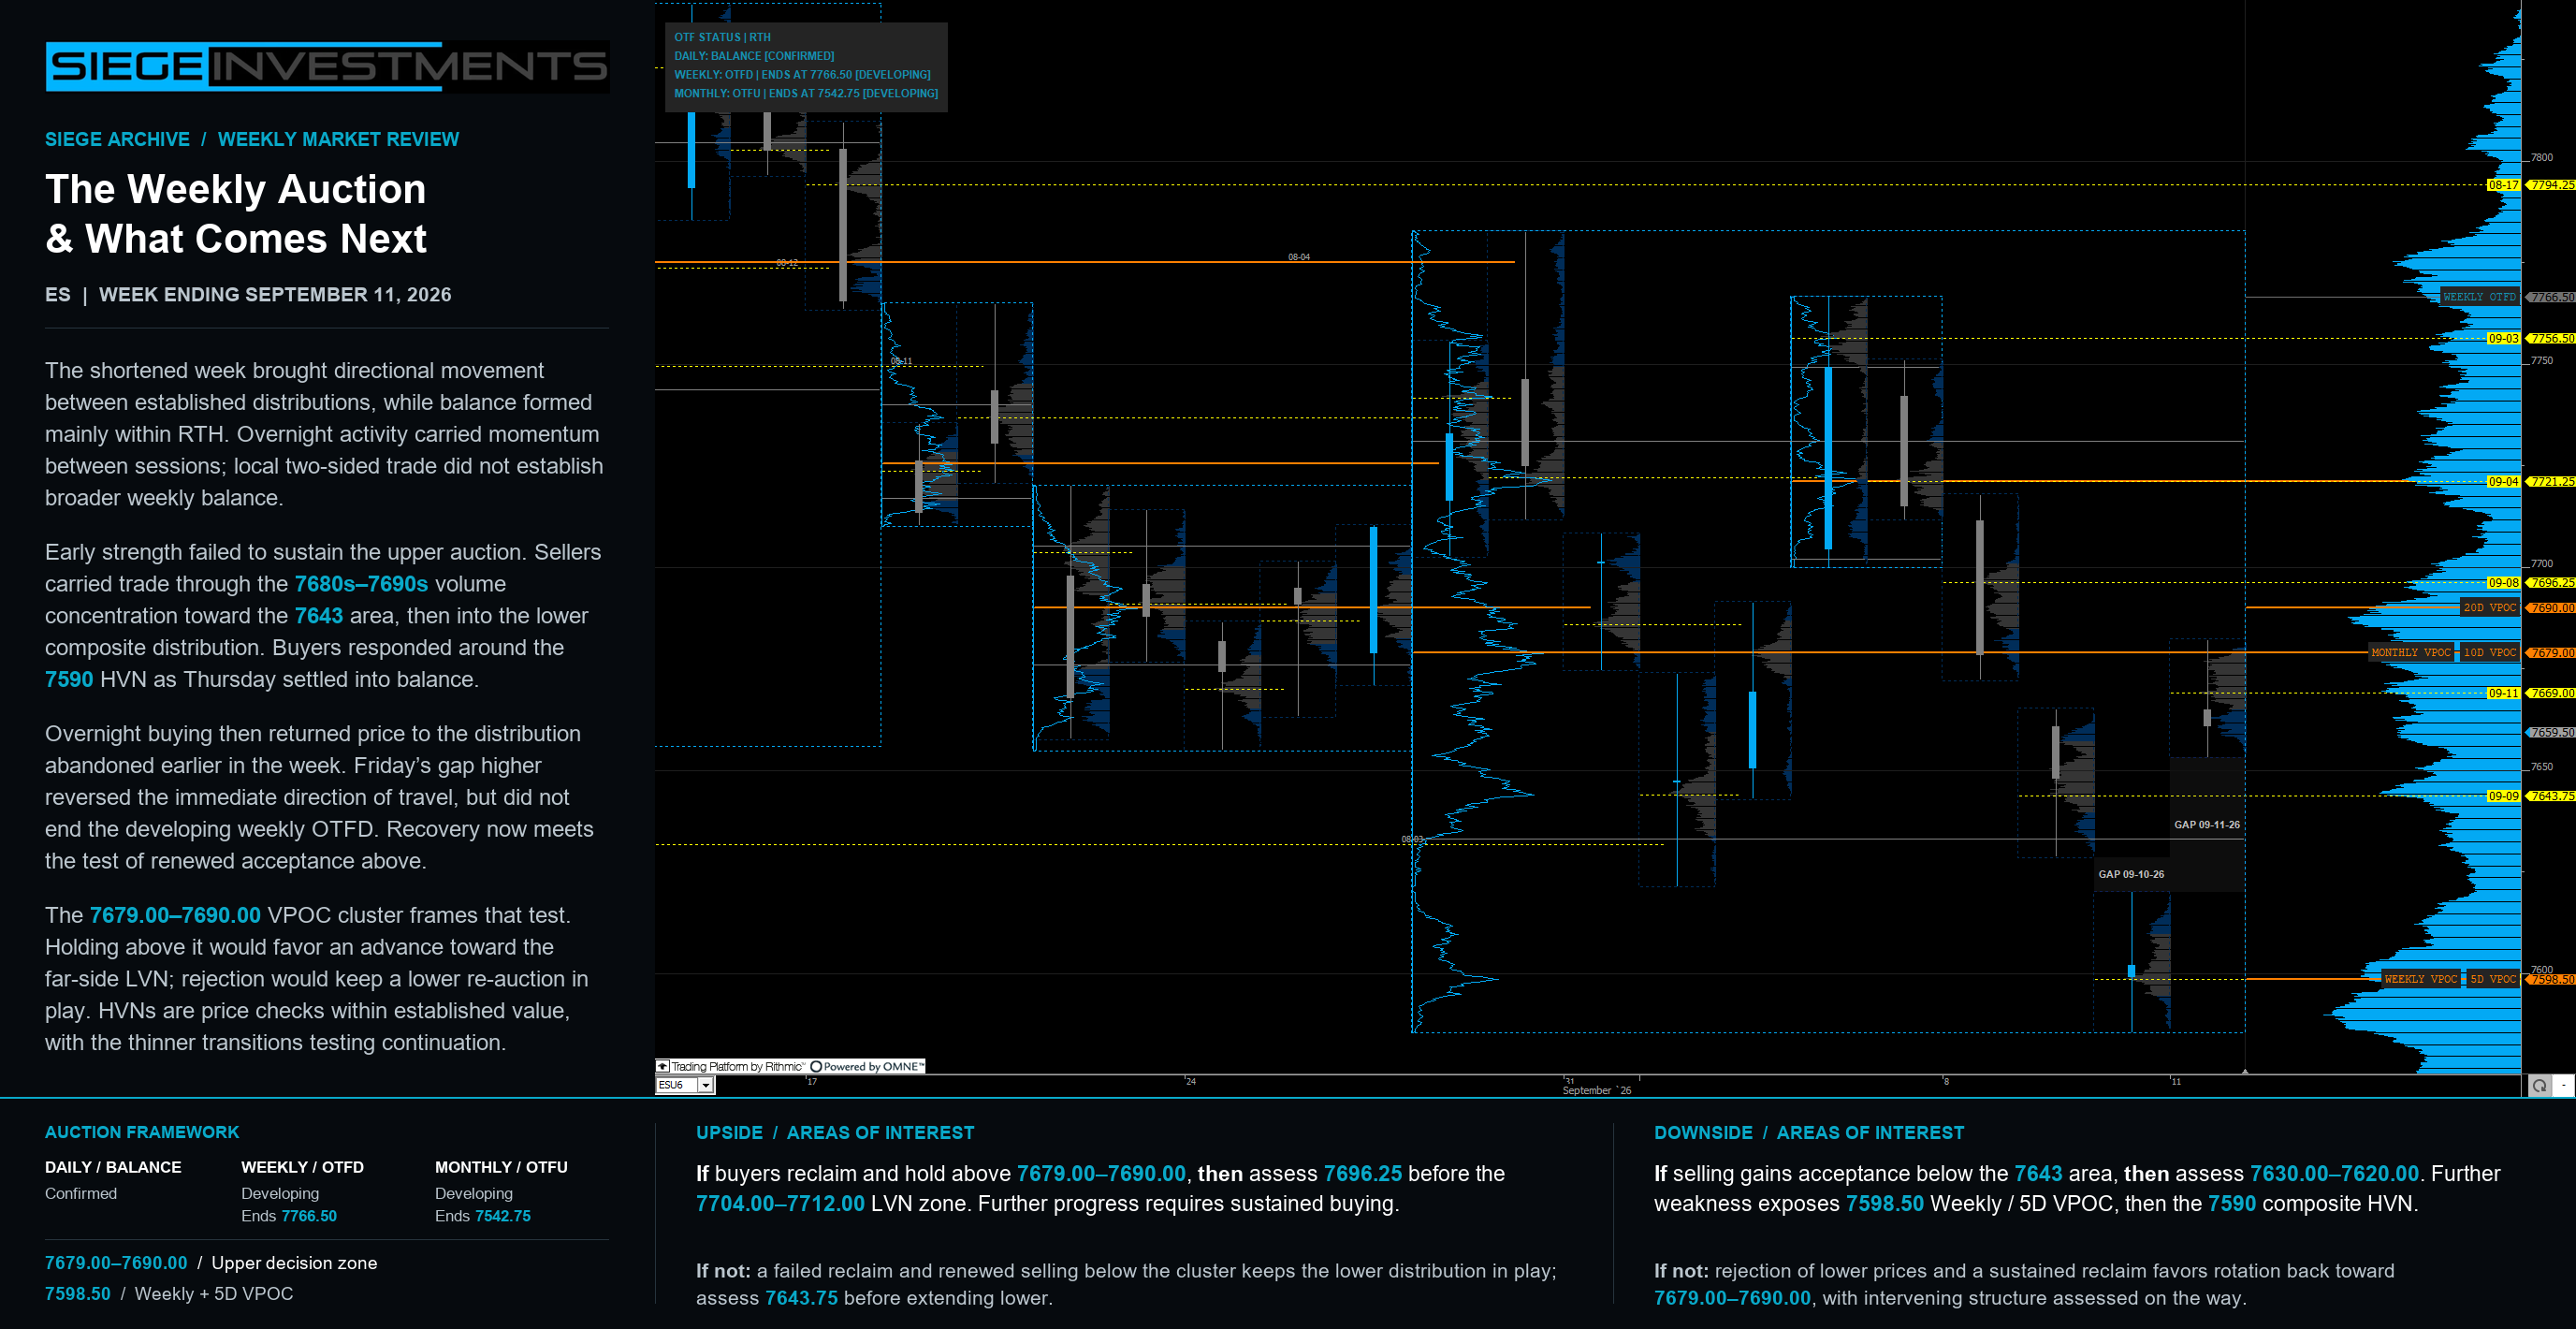
The shortened week was defined by a separation between session behavior and the broader auction. RTH repeatedly settled into two-sided trade, while overnight activity carried momentum into the next session and repositioned the market within the larger composite. Those pauses created local balance, but they did not resolve the developing weekly down auction. The distinction matters: an orderly intraday rotation can coexist with directional movement across several sessions.
The early attempt higher did not produce a sustained upper auction. The lower-volume transition initially served as a pivot into the 7680s–7690s concentration of historical volume, but buyers were unable to maintain that progress. Sellers subsequently carried trade through that area and toward the next meaningful price check around 7643. The significance was the market’s ability to leave one established distribution and continue into the next, rather than simply rotate around the same center of volume.
The intervening profile was uneven, with successive pockets of volume separated by thinner areas. Each pocket offered another test of whether two-sided trade would arrest the move or whether sellers could sustain the traverse. An HVN identifies a location where substantial business has previously occurred; it does not guarantee that the next visit will hold. This week, the initial lower price checks did not prevent a deeper exploration of the composite.
Buyers responded as the auction swept the composite HVN around 7590, followed by balance through the remainder of Thursday’s RTH session. The chart separately locates the Weekly and 5D VPOCs at 7598.50. These references sit within the same broader lower distribution, but they are not interchangeable: 7590 is the composite HVN identified in the review notes, while 7598.50 is the explicitly labeled VPOC confluence.
Thursday’s response interrupted the immediate downside progression. The subsequent overnight buying then carried price back toward the distribution abandoned earlier in the week, with Friday opening on a gap higher. That recovery returned the upper references to relevance, but a return to an old distribution is only the beginning of the next test. Buyers still need to demonstrate that trade can be sustained at higher prices.
Friday’s recovery therefore leaves two distinct observations in place: the daily auction is back in confirmed balance, while the weekly OTFD remains developing. The chart marks 7766.50 as the weekly OTFD termination reference. Monthly OTFU also remains developing, with its termination reference at 7542.75. These describe the timeframe structure; they are not automatic objectives for the coming week.
The immediate upper decision area spans 7679.00–7690.00. The lower reference combines the Monthly and 10D VPOCs; the upper reference is the 20D VPOC. Together they frame the multi-timeframe volume concentration highlighted in the weekly notes. This is a confluence zone, not a measured value-area boundary.
If buyers reclaim that area and sustain trade above it, then 7696.25 is the next visible overhead price check before the previously identified 7704.00–7712.00 LVN zone. The thinner far side of the distribution becomes a meaningful pivot only after the intervening business has been traversed. Continued buying must qualify each extension; a brief push through the cluster is insufficient on its own.
If not, a failed reclaim followed by renewed selling below the cluster keeps rotation toward the lower references in play. The 7643 area is the next major volume check discussed in the weekly notes, with 7643.75 explicitly marked on this chart. A response there must be assessed before assuming another complete traverse lower.
If sellers establish acceptance beneath that area, then the previously identified 7630.00–7620.00 LVN zone becomes relevant. Sustained weakness through that transition would bring the 7598.50 Weekly/5D VPOC confluence and the composite HVN around 7590 back into focus. The chart shows intervening gap regions, but their exact completion ticks are not printed clearly enough to add as numerical targets.
If not, rejection of the lower probe and a sustained reclaim of the 7643 area would weaken the continuation case and reopen the route toward 7679.00–7690.00. The task is to observe whether each test attracts durable two-sided trade or whether price continues through it. Historical volume provides the locations; the developing response determines which scenario remains valid.